SEOUL, Aug. 4 (Yonhap) — South Korea’s new COVID-19 cases stayed above 100,000 for the third straight day Thursday amid a fresh wave of infections driven by a highly infectious omicron variant. The country added 107,894 new COVID-19 infections, including 435 from overseas, bringing the total caseload to 20,160,154, the Korea Disease Control and Prevention Agency (KDCA) said. Thursday’s figure fell from the 119,922 the previous day, which was the highest since the 125,822 cases reported April 15. The daily caseload was 1.22-times higher than the 88,374 reported a week ago and 1.52-times more than the 71,142 cases from two weeks ago on the spread of the now-dominant omicron variant BA.5. Health authorities warned people to take precautions as the number of seriously ill patients rose to 310, the highest figure since May 18, when the tally stood at 313. The KDCA reported 34 deaths from COVID-19, raising the death toll to 25,144. The fatality rate was 0.13 percent. Among the 172 deaths reported from July 24-30, 167, or 97.1 percent, are aged over 50. Of the 167 people, 61, or 36.5 percent, were either unvaccinated or had received only one shot, the KDCA said. NN: this does not lok good for the coming US and European Covid season starting this fall…
A red-hot July jobs number has traders penciling in another jumbo Fed rate hike
Goldman, Bernstein strategists say stocks rally can fizzle out
https://www.bnnbloomberg.ca/goldman-bernstein-strategists-say-stocks-rally-can-fizzle-out-1.1801337
https://www.bnnbloomberg.ca/goldman-bernstein-strategists-say-stocks-rally-can-fizzle-out-1.1801337
The recent brisk rebound in equity markets won’t last as the macroeconomic data continue to deteriorate and earnings forecasts are being slashed, strategists at Goldman Sachs Group Inc. and Sanford C. Bernstein warn. “Without clear signs of a positive shift in macro momentum, temporary re-risking could actually increase risks of another leg lower in the market rather than signal the end of the bear market,” Goldman strategists led by Cecilia Mariotti wrote in a note dated Aug. 4. \With investors once again flocking to equities in recent weeks, Goldman strategists said market positioning has improved from a very bearish level seen in June, and the swing in asset allocation could fuel the rally in the short term. But ultimately, strategists said they’re “not convinced that we are past the ‘true’ trough in positioning just yet, and we think the path from here is likely to become more dependent on macroeconomic data.” Bernstein strategists Sarah McCarthy and Mark Diver said in a note on Thursday that the earnings downgrade cycle is just starting along with outflows from stock funds. While investors have stopped buying equities in the second quarter, funds haven’t yet seen a reversal of the “huge” inflows of US$200 billion seen in the first quarter, they said.
“We expect another leg down in the market in the short run,” Bernstein strategists wrote.
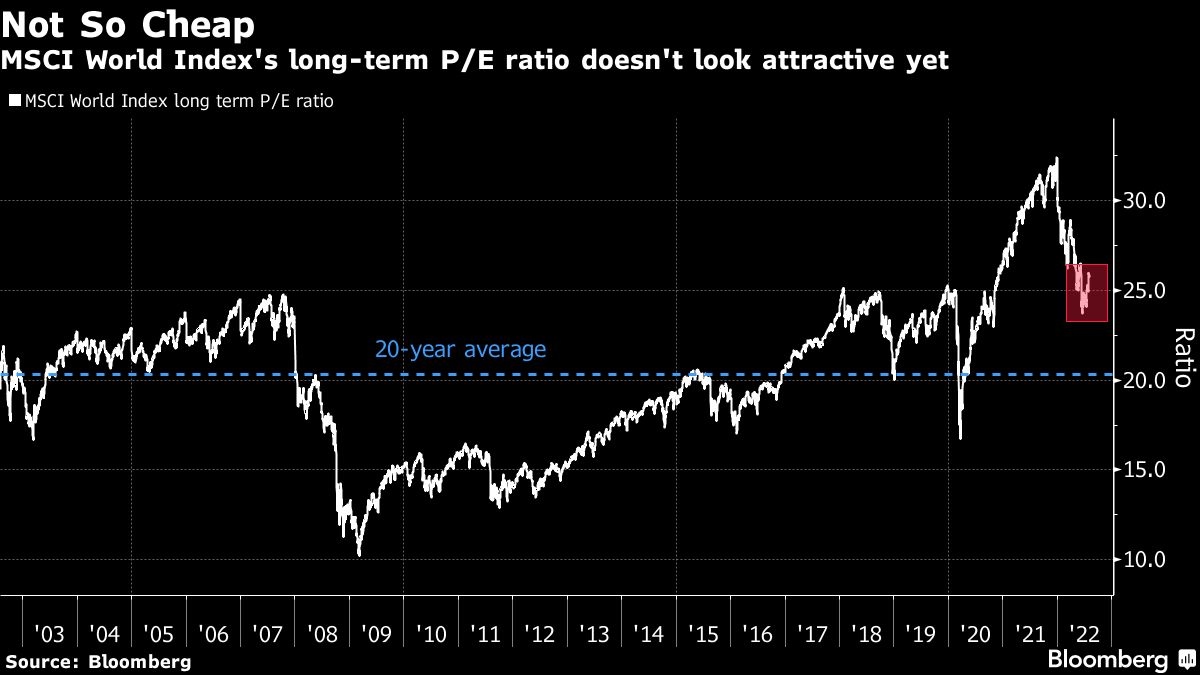
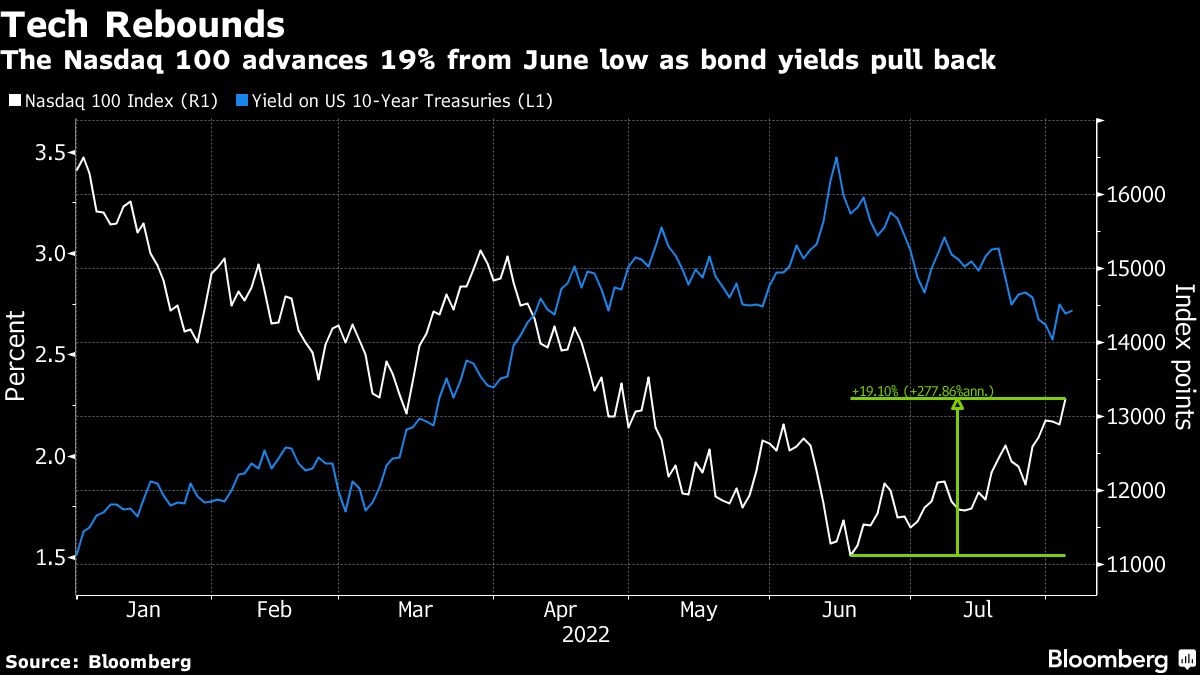
European and US stock markets in July posted their biggest monthly gains since 2020 as investors turned optimistic about corporate earnings proving resilient to surging inflation and a glum consumer outlook, while weaker economic data increased bets on a dovish pivot by the Federal Reserve. The drop in bond yields has fueled a 19 per cent bounce in the Nasdaq 100 from its June lows. But with Federal Reserve leaders pledging to continue an aggressive fight to cool inflation despite recession risks, strategists have cautioned against assuming a sustained recovery in stock markets. And although corporate earnings have been much better than feared this season, the likes of Morgan Stanley and Bank of America Corp. strategists have said that profit estimates will need to see much stronger cuts before stocks can find a true low.
Berenberg strategists Edward Abbott and Jonathan Stubbs also warned of the threat to equities from weaker earnings to come. The strategists’ top-down model showed corporate earnings are likely to fall 15 per cent to 20 per cent year-over-year as margins come under pressure, they wrote in a note dated Aug. 3. NN: Going for broke. I got it all on the line betting that this bear market rally ends in tears as in new stock market lows. Starting next week i will recommend you short this stock market rally using ETF’s, Futures and CFD’s through a English trust…..,,,,, AND I COULD BE WRONG AND WE COULD ALL LOSE A BUNDLE. This is not savings, this is not investing… it even beyond gambling…. This is worse odds then the power ball lottery,
odds are 1 in 88 quadrillion
Now that is my kind of gamble!!!!
Oil rout deepens as U.S. crude benchmark falls below $90 a barrel
Oil futures extended a decline Thursday, with Brent crude slipping to levels last seen before Russia’s invasion of Ukraine and the U.S. benchmark sliding below the $90-a-barrel threshold. Oil is building on losses seen on Wednesday after the Energy Information Administration said U.S. crude supplies rose 4.5 million barrels in the week ended July 29, while gasoline supplies rose 200,000 barrels — both had been expected to fall.
“The oil market is a mixed bag as demand destruction is met with limited spare capacity. Ongoing weakness should be unlikely since the oil market remains tight, but the break of key technical $90 level could unleash some momentum selling,” said Edward Moya, senior market analyst at Oanda, in a note.
“WTI crude should have seen massive support at the $90 a barrel level, but an intensifying global economic slowdown is changing that oil market is tight trade. WTI crude should see some support at the $88.75 if this breach of the $90 level holds,” he wrote. Oil fell sharply in volatile trade Wednesday, giving up early gains seen in the wake of a meager increase in output by the Organization of the Petroleum Exporting Countries and its allies — a group known as OPEC+ — to tumble sharply after the Energy Information Administration said U.S. crude supplies were up 4.5 million barrels in the week ended July 29, while gasoline supplies rose 200,000 barrels. The price action shows that “demand concerns are now the dominant influence on the global energy market and even though supply worries will persist with the Russia-Ukraine war, we will need to see evidence of demand stabilizing for the oil market to begin to find a near-term bottom,” wrote analysts at Sevens Report Research, in a note. NN: this is hype… the market is under-supplied and it will get worse as more sanctions are coming on Russian crude oil delivered by ship. Let me show you what i mean by hype. Gasoline prices reached a record high of $4.81…. Now at $4.14 a gallons as vacation driving season winds down. What they forget to tell you is the fact gasoline was $3.19 a gallon a year ago. And two years ago in most US markets under $3.00…. What price drop?
Stocks Waver on Fedspeak, Disappointing Earnings: Markets Wrap
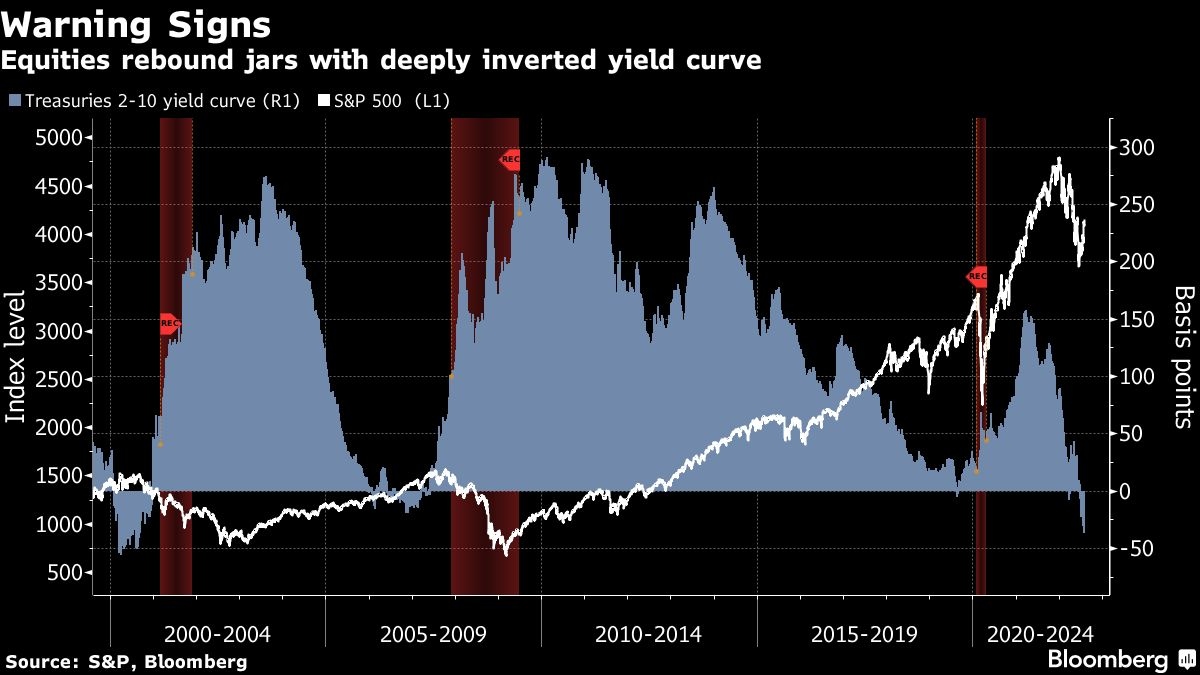
US stocks wavered on Thursday as traders parsed various corporate earnings against a backdrop of aggressive interest-rate hikes by global central banks. The US yield curve remained inverted as recession fears persisted. The S&P 500 ended the session little changed after fluctuating throughout the session. The Nasdaq 100 closed up higher for the second straight day after swinging between modest gains and losses. While the tech-heavy index was buoyed by Amazon.com Inc. and Advanced Micro Devices Inc. later in the session, it was also dragged down by Fortinet Inc. after the firm trimmed its service-revenue forecast. Eli Lilly & Co., which dropped after missing Wall Street expectations for second-quarter revenue, weighed on the S&P 500 Index. Thin liquidity in the summer also tends to amplify market moves. Treasury yields wobbled throughout the session, with the 10-year rate around 2.66 per cent after pushing past 2.80 per cent on Wednesday. A flurry of economic data that released this week assuaged fears of a downturn while hinting at stabilizing growth. But the bond market, especially the persistently inverted Treasury yield curve, is flashing warnings on the economy amid a global wave of monetary tightening. All eyes will be on the US jobs report on Friday for further clues about the Federal Reserve’s path of rate hikes. “There’s an intense tug-of-war happening in the economy and markets,” said Dan Suzuki, deputy chief investment officer at Richard Bernstein Advisors. “On one side, you have a narrative that reasonable growth is going to support continued inflation pressure and keep the Fed hiking. The other narrative is that slowing growth is going to ease inflation and allow the Fed to stop hiking.”
On Thursday, Cleveland Fed President Loretta Mester reiterated the central bank’s promise to bring down inflation by raising interest rates. Her counterparts, this week, have also been backing this hawkish stance, forcing markets to recalibrate after initially expecting a dovish pivot Fed Chair Jerome Powell hinted at last week.
US-China tension also remains among the uncertainties clouding the outlook. China likely fired missiles over Taiwan during military drills on Thursday, Japan said, part of Beijing’s biggest cross-strait exercises in decades after US House Speaker Nancy Pelosi visited the self-ruled island. West Texas Intermediate stayed below US$90 a barrel, a level last seen in the weeks leading up to Russia’s invasion of Ukraine. Gold advanced and Bitcoin fell.
Is anyone Listening…. Bank of England predicts massive inflation continuing AND a recession throughout 2004…
he UK is set to fall into it longest recession since the financial crisis and inflation will peak at more than 13% as gas prices soar, the Bank of England has warned. Decision makers hiked the Bank’s base interest rate to 1.75% from 1.25%, the biggest single rise since 1995, as they tried to control the runaway inflation. Consumer Prices Index inflation will hit 13.3% in October, the highest for more than 42 years, if regulator Ofgem hikes the price cap on energy bills to around £3,450, the Bank’s forecasters said.

The energy price will push the economy into a five-quarter recession – with gross domestic product (GDP) shrinking each quarter in 2023. “Growth thereafter is very weak by historical standards,” the Bank said on Thursday. The dire economic conditions will see real household incomes drop for two years in a row, the first time this has happened since records began in the 1960s. They will drop by 1.5% this year and 2.25% next. However, the recession will at least be shallower than the 2008 crash, with GDP dropping up to 2.1% from its highest point.
The Monetary Policy Committee voted by a majority of 8-1 to increase BankRate to 1.75%. Bank officials said that the depth of the drop is more comparable to the recession in the early 1990s. Unemployment will start to rise again next year, according to the projections. The Bank said that it expects inflation to come back under control in 2023, dropping below 2% towards the end of the year.
“The United Kingdom is now projected to enter recession from the fourth quarter of this year,” the Bank’s Monetary Policy Committee (MPC) said.
“Real household post-tax income is projected to fall sharply in 2022 and 2023, while consumption growth turns negative.” GDP is set to grow by 3.5% this year, the Bank said, revising its previous 3.75% projection downwards. It will then contract 1.5% next year, and a further 0.25% in 2024.
Inflation is over 9%. We expect it to rise further this year to around 13%, due to higher energy bills.
Meanwhile, real post-tax household income will fall 1.5% this year and 2.25% next, it said. It puts rates at their highest point since January 2009. The MPC said that pressures from inflation had intensified since the last time the committee met, largely due to a near doubling in wholesale gas price since May. As this feeds through to energy prices, households will face a major squeeze on their budgets.The Bank forecast that the price cap on energy bills will rise from £1,971 to £3,450 per year for the average household this October. NN;
Robinhood to lay off 23% of its workforce
CEO says company’s staffing levels don’t match up with current depressed trading environment
Robinhood Markets Inc. plans to cut its staff by 23%, citing the weakening economic environment and depressed trading activity. Chief Executive Vlad Tenov publicly announced the layoffs in a Tuesday afternoon blog post, acknowledging that his prior plan to let go of 9% of the Robinhood HOOD, +2.10% workforce while engaging in “greater cost discipline,” which was announced in April, “did not go far enough.” “Since that time, we have seen additional deterioration of the macro environment, with inflation at 40-year highs accompanied by a broad crypto market crash,” Tenov said. “This has further reduced customer trading activity and assets under custody.” Shares of the company were off 1% in after-hours trading Tuesday. Tenov shared in the post that Robinhood “staffed many of our operations functions under the assumption that the heightened retail engagement we had been seeing with the stock and crypto markets in the COVID era would persist into 2022,” and that the company now has “more staffing than appropriate.” The layoffs are expected to impact employees in all functions, but mostly those in operations, marketing and program management. The blog post came after a companywide meeting and indicated that staffers would learn of their status via email and Slack “immediately” after that meeting so that employees “don’t have to wait for clarity.” “As CEO, I approved and took responsibility for our ambitious staffing trajectory – this is on me,” Tenov said. Also on Tuesday, Robinhood reported second-quarter financial results, which arrived a day earlier than scheduled. The company posted a net loss of $295 million, or 34 cents a share, compared with a loss of $392 million, or 45 cents a share, in the year-prior quarter. Revenue climbed 6% to $318 million. Robinhood also disclosed in its earnings release that monthly active users fell by 1.9 million sequentially “as customers navigated the volatile market environment” while assets under custody dropped 31% sequentially to hit $64.2 billion. NN: Looks like the Sheriff of knottingham shot a arrow in their ass……
markets may see three-month string of 8.8% inflation readings starting next week
The financial market’s most knowledgeable inflation traders are expecting a string of roughly 8.8% annual headline U.S. consumer-price readings over the next three months, starting with the Aug. 10 release of July’s data. While such readings would be below June’s 9.1% reading and support the theory that inflation may have peaked at an almost 41-year high, the expectations of inflation-derivatives traders still adds up to what could be a lot of bad news for the broader market. The reason boils down to the length of time that high U.S. inflation persists, which would upend the hopes of investors, traders and policy makers for a relatively quicker and meaningful slowdown in price gains. The string of 8.8% figures — broken down as 8.78% for July, 8.75% for August and 8.79% for September — already takes into account the recent decline in gas prices, along with a drop in commodities such as wheat W00, -3.28%, and would come while the Federal Reserve is in the midst of an aggressive rate-hike campaign. Hopes that inflation may have peaked in June may be obscuring the risk that a wage-price spiral could still develop and that price gains in other areas, like shelter, could accelerate or remain sticky, some say.
“It’s bad news to have inflation last so high for so long,” said Derek Tang, an economist at Monetary Policy Analytics in Washington. “The longer high inflation lasts, the more worried Fed officials get that inflation expectations are getting unanchored, and they can’t allow that.”
While much still depends on labor-market data and whether a wage-price spiral unfolds, “people are going to price in a higher fed funds rate for the end of year and rate hikes lasting longer into 2023, with the first rate cut not happening until later,” Tang said via phone on Tuesday. Three annual headline CPI prints of essentially 9% “make it hard to see how the Fed is going to start cutting rates in 2023. Inflation that starts to come down is good, but the question is, ‘Does it come down soon enough?’ The Fed has a window to prove it’s going to bring inflation down, and people are going to start losing faith in that story.”
For the time being, financial markets appear to be broadly accepting the idea that the central bank will more or less get a handle on inflation in the long run: Five-, 10- and 30-year breakeven rates remain contained within a range of 2.2% to 2.7%, while yields on Treasury inflation-protected securities are off their multi-year highs but moved up on Tuesday, according to Tradeweb data. In addition, all three major U.S. stock indexes DJIA, -1.23% SPX, -0.67% COMP, -0.16% are off the lows they reached in June, when inflation fears dominated.
After a jump in growth and technology-related stocks in July, there’s now a question over how recessionary risks will weigh on their recent bear-market rally. Ed Perks of Franklin Templeton Investment Solutions said in a phone interview late last week that the market may be looking through “rose-colored glasses.” “We still have pretty tough sledding ahead of us,” he added. On Tuesday, major stock indexes finished lower as investors also factored in geopolitical risks between the U.S. and China. Meanwhile, two- and 10-year Treasury yields posted their biggest gains since June as investors aggressively sold off government debt, reversing course from earlier in the day. “If we are going to get a labor/price shock, equities might be affected very heavily,” Tang of Monetary Policy Analytics told MarketWatch. Soaring labor costs heading into economic weakness “is going to hit revenues and could be an issue for profit margins.”
“The bigger issue is that the market may be misunderstanding how serious the Fed is about inflation,” he said. “It may be wishful thinking to think the Fed can bring it back down to 2%.”
On Tuesday, top officials at the Fed said the central bank needs to raise interest rates a lot higher and probably keep them high for awhile to contain the worst outbreak of inflation in almost 41 years
U.S. job openings drop below 11 million
First time since last fall as hiring slows
Lots of companies are still trying to hire, but many are pulling back and there’s been some reports of scattered layoffs, especially in the tech sector. The number of people applying for unemployment benefits has also risen slightly in the past few months. As long as the U.S. avoid mass layoffs, the economy is likely to keep growing or at least avert a steep recession. But there’s no guarantee with inflation running rampant and the Federal Reserve sharply raising interest rates. Job openings fell the most in retail (-343,000), wholesaling (-82,000) and state and local government (-62,000). Most other industries saw little change. The so-called quits rate was unchanged at 2.8%. It peaked at 3% at the end of 2021. More people quit when the economy is doing well or they think they can find a better a job. There’s almost two open jobs for every unemployed person, though companies never try to fill all of them. The number of job openings is largely viewed as a way to assess the strength of the labor market. The government’s job-openings report is released with a one-month lag. “If the economy is rolling over, the labor market had apparently not gotten the memo yet as of the end of June,” said chief economist Stephen Stanley of Amherst Pierpont Securities. “The outlook for economic growth may not be as rosy as it was a few months ago, but there’s no sign of imminent danger in the labor market,” said Nick Bunker, director of economic research at Indeed Hiring Lab. NN: Remember the masses have still not blown YET all their happy check money. Layoffs at Robin Hood trading tell me the stock market fantasy of the millennials has blown up in their faces,,,, But the wake up call is far from over….. They have never seen a recession, mass layoffs, a prolonged bear market and a recession leading to a depression…. You can se why they want to live in the altered reality metaverse…….
The Fed vowed to crush inflation with higher rates. Then the stock market rallied
Slaying the inflation dragon isn’t done with baby steps. Expect much higher interest rates as a headwind for equities.
‘‘We are now at levels broadly in line with our estimates of neutral interest rates, and after front-loading our hiking cycle until now we will be much more data-dependent going forward.’’
— Jerome Powell, July 2022 FOMC press conference
The Federal Reserve on Wednesday raised interest rates by another 75 basis points despite acknowledging that economic growth is clearly slowing. The central bank, under Powell, reiterated that the path of least resistance is well-represented by the so-called dot plot: More hikes ahead — all the way to a fed funds rate of 3.75%! And yet, the stock market has staged a humongous rally, led by the most valuation-sensitive and risk-sentiment-driven asset classes: Nasdaq stocks COMP, +1.88% and crypto. It all boils down to how one single sentence was able to affect the probability distributions that investors were projecting for different asset classes. When the FOMC’s press release was published, it looked like business as usual: A well-telegraphed 75-bp hike with the only small surprise represented by an unanimous vote despite clear acknowledgment that economic growth is softening. But not even 15 minutes into the press conference, the fireworks went off! In particular, when Powell said: ‘‘We are now at levels broadly in line with our estimates of neutral interest rates, and after front-loading our hiking cycle until now we will be much more data-dependent going forward.’’
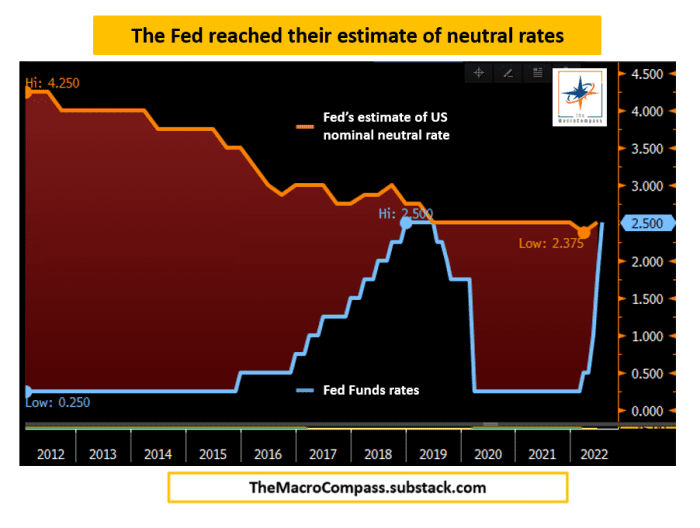
This is very important for several reasons. The neutral rate is the prevailing rate at which the economy delivers its potential GDP growth rate — without overheating or excessively cooling down. With this 75-bp hike, Powell told us the Fed just reached its estimate of a neutral rate and, hence, from here they aren’t contributing to economic overheating anymore. But that also means any further increases are going to put the Fed in an actively restrictive territory. And the bond market knows that every time the Fed became restrictive in the past, they ended up breaking something.
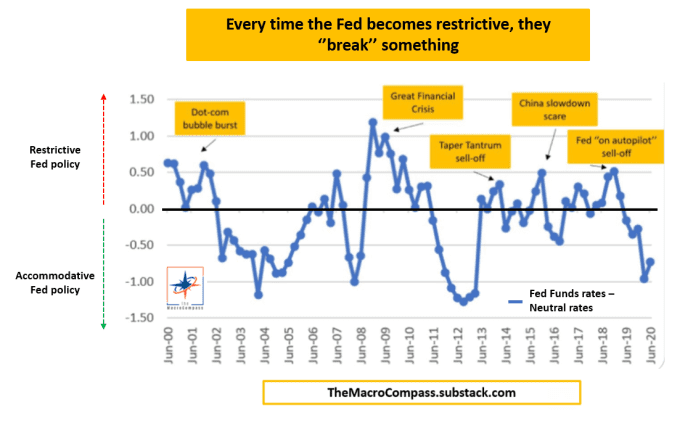
Until Wednesday, you could be completely sure that the Fed would have just pressed on the accelerator — inflation must come down; no space for nuance. So journalists asked questions to find out something about the ‘‘new’’ forward guidance. It went roughly like this: Journalist: ‘‘Mr. Powell, the bond market is pricing you to cut rates starting in early 2023 already. What are your comments?’’ Powell: ‘‘Hard to predict rates six months from now. We will be fully data-dependent.’’ Journalist: ‘‘Mr. Powell, due to the recent bond and equity market rally, financial conditions have eased quite a lot. What’s your take?’’ Powell: ‘‘The appropriate level of financial conditions will be reflected in the economy with a lag, and it’s hard to predict. We will be fully data dependent.’’ He did it. He totally ditched forward guidance. And what happens when you do so? You give markets the green light to freely design their probability distributions across all asset classes without any anchor — and that explains the gigantic risk rally — as well as the jump in the broader S&P 500 SPX, +1.42%. If the Fed is so data-dependent, and there is basically one data they care about, it all boils down to how inflation will evolve in the near future — and the bond market has a very strong opinion about that.
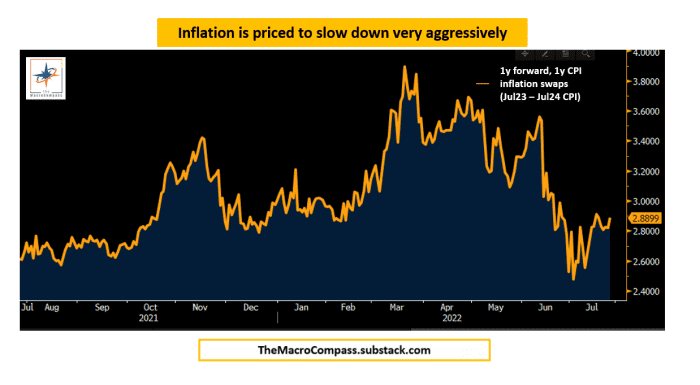
The expected inflation between July 2023 and July 2024, which is represented in the chart above and sits at 2.9%. Remember that the Fed targets (core) PCE, which tends to historically be 30-40 bps below (core) CPI: Essentially, the bond market expects inflation to slow very aggressively and roughly hit the Fed’s target in the second half of 2023 already! So if the Fed is not nearly on autopilot anymore, and markets have a strong opinion on inflation and growth collapsing, then they can also price all other asset classes around this base case scenario. It starts to be more clear now, right? If the Fed isn’t going to blindly keep hiking rates but be more data-dependent, contingent on their view that CPI will quickly come down, traders have a green light to price a more nuanced tightening cycle and, hence, still expect restrictive real yields but less so than before. When real yields decline, valuation-sensitive and risk-sentiment-driven asset classes generally tend to outperform. That’s because the marginal inflation-adjusted return for owning cash USDs (risk-free real yields) becomes less attractive and the (real) discounting rate for long-term cash flows becomes much less punitive. Thus, the incentive to chase risk assets is larger — actually, following this narrative one could argue that ‘‘the riskier, the better.” Here is a chart showing the very tight relationship between real yields and equity market valuations.
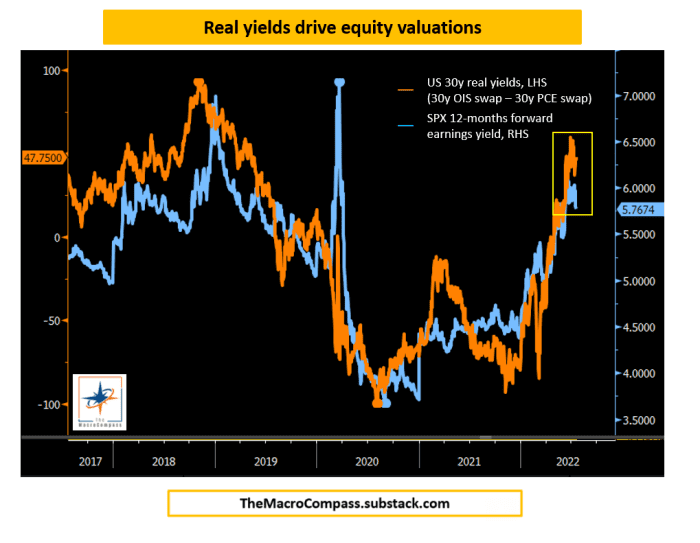
So guess who the two main characters of the crazy market rally were? U.S. tech and crypto. But let’s now answer the real question: In this giant puzzle called global macro, are all the pieces falling into the right place to fully support this narrative? In short, the crazy market rally was spurred by Powell ditching the Fed’s forward guidance and kickstarting ‘‘full data-dependency’’ season. Given the bond market’s strong opinion on inflation going forward and no autopilot by the Fed on a tightening cycle, investors went ahead and repriced all other asset classes accordingly. If the Fed isn’t going to blindly hike us into a recession, and contingent on inflation slowing quickly as priced in, then:
- Fewer hikes now, fewer cuts later (curve steepening)
- Lower real yields (Fed won’t keep policy ultra-tight for too long)
- Risk-sentiment-driven asset classes can rally
So does the new narrative pass the global macro consistency test? Not really. Not yet. And for two main reasons.
1. This is the most important inflation fight that central bankers have engaged in over 35 years, and history suggests a ‘‘mildly’’ restrictive stance won’t be enough.
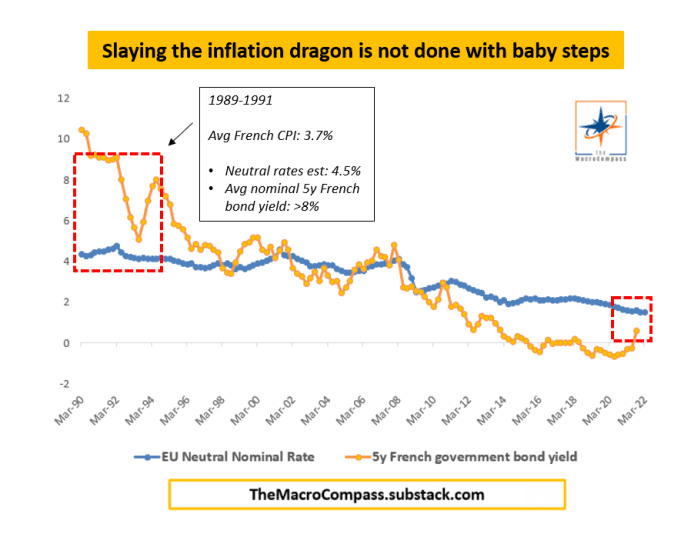
Slaying the inflation dragon is generally not done with baby steps, and that’s been true across different jurisdictions and historical circumstances. For instance: The last time inflation was stubbornly high in France, the central bank had to bring nominal yields (orange) all the way to 8% and keep them there for years to bring down CPI — way above my the prevailing neutral rate (blue) at 4.5%. Assuming the Fed will be able to engineer significantly lower inflation while already taking the foot off the gas pedal seems very optimistic.
2. Ditching forward guidance increases volatility in bond markets even further, and a volatile bond market is an enemy for risk assets. Let’s assume the next inflation print is worse than expected in absolute terms, momentum and composition. A fully data-dependent Fed will have to consider a 100-bp hike in September: Very likely to generate mayhem in markets all over again. While ditching forward guidance might be the right monetary policy strategy amid these uncertain times, when there is no anchor for bond markets, implied volatility will have a hard time falling. And higher volatility in one of the biggest, most liquid markets in the world generally requires higher (not lower) risk premia everywhere else. To sum it all up: The Fed can’t, and won’t, stop until the job is done. And the job will be done only when inflation has been killed — with likely big collateral damage inflicted on the stock market, labor market and the broad economy too.