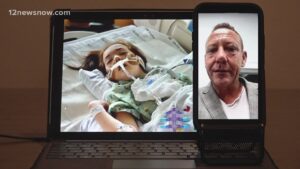
(Sept. 20) Pfizer Inc. and partner BioNTech SE said their Covid-19 vaccine was safe and produced strong antibody responses in children ages 5 to 11 in a large-scale trial, findings that could pave the way to begin vaccinating grade-school kids within months. The long-awaited results offer one of the first looks at how well a Covid vaccine could work for younger children. Pressure to immunize kids has been on the climb in the U.S., where a new school year has started just as the delta variant is fueling a surge in cases. In a trial with 2,268 participants, two shots of a 10 microgram dose — one-third the adult shot — produced antibody levels comparable to those seen in a trial of 16-to-25-year-olds who got the adult dose, the companies said, with similar side effects. Nick Note: The rate of infection and hospitalizations among the kiddies are soaring. The story they are not telling you…
HARD TO LOOK AT
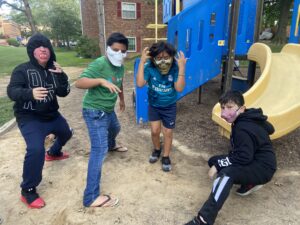
Kids are getting infected and hospitalized and dieing. School should be out until vaccinations. Best case that is not going to happen until year end. I am working on my fun cool mask for kiddies. I will soon have product for you. The idea was to make a fun cool mask the kiddies would wear. We started with a 5 layer replaceable N95 certified filter. I got with my premed student Nichole and gave her this product. She made a bunch of the cool N95 fun masks and took them to the local playground and the kiddies went wild….
US equities rebounded firmly early Tuesday, as Wall Street looked to bounce back from its worst day in four years. Just after 1500 BST, the Dow Jones Industrial Average was up 332 points to 16,203.66, while the S&P 500 and the Nasdaq 100 were 43 and 128 points higher respectively.
“After the market-wide panic of ‘Black Monday’, cooler heads seem to be prevailing this Tuesday morning, as investors begin to pick up the pieces, even if China itself continues to struggle,” said Connor Campbell, financial analyst at Spreadex.
Chinese shares closed lower on Tuesday, although other stocks in the region began to rebound from “Black Monday”. The Shanghai Composite closed down 7.63%, despite the People’s Bank of China injecting a $24bn boost to ease the pressure the index was under. The Shanghai Composite closed down 7.63%, despite the People’s Bank of China injecting a $24bn boost to ease the pressure the index was under. Meanwhile, the People’s Bank of China cut interest rates for the fifth time since November in a bid to buoy its flagging economy. The PBOC lowered its benchmark lending and deposit rates by 0.25 percentage point, adding that the rate cuts will become effective on 26 August and are aimed at reducing corporate borrowing costs. China’s central bank also reduced its reserve requirement ratio by 0.5 percentage points, starting from 6 September, adding the cuts are meant to ensure enough liquidity and stable credit growth. “The fact that the PBOC can use the reserves requirement ratio cut as a buffer in this way underlines why recent concerns about the destabilising impact of capital outflows on China’s economy are overdone,” said Mark Williams, chief China economist at Capital Economics. “The reserves requirement ratio of return for large banks still stands at 18.0% after this move.” On the economic data front, the Markit composite Purchasing Managers Index declined slightly in August, figures released on Tuesday showed. The index fell 0.7 points to 55.0, while the sub-index monitoring the services sector slid from 55.7 to 55.2, marginally ahead of expectations for a 55.1 reading. US consumer confidence jumped from 90.9 to 101.5 in August, well ahead of expectations for a 93.4 reading, its second-highest reading since the recession. “The rebound in this month’s survey is reassuring given the recent volatility in financial markets and the sharp decline in confidence observed last month, which was driven in part by concerns over Chinese growth,” Barclays‘ analysts said in a note. “In addition, after a weak employment outlook last month, consumers were considerably more confident in the job market in August, giving us confidence in our positive employment outlook.” Meanwhile, according to the S&P Case-Shiller 20-city composite index, after seasonal adjustment prices declined 0.1%, while prices in June were up 5% year-on-year, little changed from May. Sales of new single-family homes rose last month, recovering from the sharp decline they suffered the previous month. According to figures released by the Commerce Department, new home sales rose 5.4% in July to a seasonally-adjusted annual rate of 507,000, after a 7.7% slump in the previous month. Analysts had expected a 5.8% increase for a 510,000 annual rate last month, compared with a downwardly revised 481,000 rate in June. In company news, Netflix jumped 8.10% after entering bear market territory on Monday, while Apple surged 5.25% after falling to a 10-month low in the previous session. Best Buy soared 14.3% after its profit and sales beat estimates. Elsewhere, European stocks recouped some of their losses, while the dollar fell 0.15% against the pound but rose 0.57% against the yen and 0.92% against the euro.Gold futures slid 0.62% to $1,146.50, while oil prices staged a solid comeback, with West Texas Intermediate climbing 3.29% to $39.54 a barrel and Brent gaining 2.84% to $43.94 a barrel. Nick Note: I as so stated in our live streaming TV… am not so sure this is the big one. I am seeing a rebound which is what i expected. We got a 5% what i am calling for now retracement from the August and early September recording breaking highs. So far every swoon has seen a rush to buy on the bottom. A 5% drop is not a correction. and a really big one is coming. As you know the real driver of the coming correction will be the Fed raising rates…. And cutting off this mindless stimulus. Until then i am the careful bear,,,,,
Sept 20 (Reuters) – U.S. stocks sharply dropped on Monday as risk-off sentiment gripped investors on concerns over the pace of global growth and a possible spillover from China Evergrande’s troubles, ahead of the Federal Reserve’s policy meeting later this week. The Nasdaq tumbled as much as 2.9% in afternoon trading, led by declines in growth names including Microsoft Corp, Google-owner Alphabet Inc, Amazon.com Inc, Apple Inc, Facebook Inc and Tesla Inc. “The potential default of the Chinese property developer could have far reaching and unexpected consequences. There’s the X-factor, the potential that ripples from one collapse could erode other sectors,” said Danni Hewson, financial analyst at AJ Bell. “If the Chinese economy is dented, what happens to demand for those nice-to-haves like a shiny new Tesla. Shares in the car company have tumbled and the Nasdaq with them, in fact the tech heavy index makes for pretty grim viewing today.” All the 11 major S&P sectors declined. Economy-sensitive industrials, financials and energy dropped between 1.9% and 4%. The banking sub-index shed 3.9%, tracking U.S. Treasury yields as worries about the default of Evergrande appeared to affect the broader market, with commodities slipping and investors flocking to the perceived safety of bonds.. Wall Street’s main indexes have been hurt this month by fears of potentially higher corporate tax rates denting earnings and have shrugged off signs inflation might have peaked. The S&P 500 is down 4.6% from its intra-day record high hit on Sept. 2 and is on track to snap a seven-month winning streak. “This is just an environment where there’s been a lot of money that has been rewarded for excessive risk taking. And now we’re seeing a little bit of that risk come off… this is classic profit taking,” said Dennis Dick, a trader at Bright Trading LLC. “I still think a big reason for (today’s selloff) is the White House and the Biden administration talking about raising the capital gains rate.” All eyes on Wednesday will be on the Fed’s policy meeting, where the central bank is expected to lay the groundwork for a tapering, although the consensus is for an actual announcement to be delayed until the November or December meetings. At 13:30 p.m. ET, the Dow Jones Industrial Average was down 772.43 points, or 2.23%, at 33,812.45, the S&P 500 was down 99.47 points, or 2.24%, at 4,333.52. The Nasdaq Composite was down 396.26 points, or 2.63%, at 14,647.71, set for its worst day since May 12. Strategists at Morgan Stanley said they expected a 10% correction in the S&P 500 as the Fed starts to unwind its monetary support, adding that signs of stalling economic growth could deepen it to 20%. The CBOE volatility index, known as Wall Street’s fear gauge, hit its highest level in over four months. Airline carriers traded mixed after the United States relaxed travel restrictions on air passengers from China, India, Britain and many other European countries who have received COVID-19 vaccines in early November. Declining issues outnumbered advancers for a 8.44-to-1 ratio on the NYSE and for a 5.54-to-1 ratio on the Nasdaq. The S&P index recorded no new 52-week high and three new lows, while the Nasdaq recorded 19 new highs and 165 new lows. Nick Note: Allow a little for sqid marks… And so far this appears to me to be a typical 5% correction off the highs. And i expect the PRC commies will come to the riscew. And Millineals will hear the Robin Hood call of the wild and follow the Reddick buy on the dip bloggesr to become the next stock market millionaire. Doing all this as you get all the free time you need to dance, fuck boys and girls, get high and drive you girlfriend to the mountans and kill her…. Just like in the Netflix movies
LONDON, Sept 20 (Reuters) – Some of Britain’s meat processors will run out of carbon dioxide within five days, forcing them to halt production, the head of the industry’s lobby group warned on Monday. A jump in gas prices has forced several domestic energy suppliers out of business and has shut fertiliser plants that also produce carbon dioxide (CO2), used to stun animals before slaughter and prolong the shelf-life of food. The shortage of CO2, also used to put the fizz in beer, cider and soft drinks, has compounded an acute shortage of truck drivers in the UK, which has been blamed on the impact of COVID-19 and Brexit.
“My members are saying anything between five, 10 and 15 days supply,” Nick Allen of the British Meat Processors Association told Sky News.
With no CO2 a meat processor cannot operate, he said. “The animals have to stay on farm, they’ll cause farmers on the farm huge animal welfare problems and British pork and British poultry will disappear off the shelves,” Allen said. “We’re two weeks away from seeing some real impacts on the shelves. On the poultry side we’re hearing they’re even tighter supplies so we might see poultry disappearing even sooner.” Allen said the government was working hard to try and resolve the issue and could hopefully persuade a UK fertiliser producer to re-start their plant. The British Retail Consortium (BRC), which represents retailers including the major supermarket groups, said the CO2 crisis added to existing pressures on production and distribution. “Retailers are working with their suppliers to resolve this issue, but government must investigate this issue as soon as possible and work with industry to ensure a solution is found quickly and problems don’t escalate further,” said Andrew Opie, the BRC’s director of food and sustainability. Foreign office minister James Cleverly said the government was looking to address short-term shortages. “We will ensure that we are able to put food on the table, obviously that is a real priority,” Nick Note: When we had the sea food factory industrial gases where critical for our operations. And when the nearest supply was two weeks away by boat and 1,500 miles you learned to pay close attenuation. The majority of our refrigeration were run on ammonia gas with huge compressors. If they went down we would turn 10 million in sea food to cat food or worse yet $1000 of fish-meal.the Cheap gases we used we would bring from the US in tanks mounted on 20 foot containers We also used a lot of Co2 gas. It was used to flash freeze fish fillets, lobster and shrimp. We had a IQF (individual quick frozen) Co2 tunnel to process shrimp. The cost of the gases was virtually nothing but you could not operate without it. We purchased from the commercial gas manufactures in Louisianan. All produced as a by product from natural gas. Co2 is used to stun chickens and turkeys before slaughter. It is used to freeze chicken parts like chicken McNuggets. The chicken, Turkey, fish and meat packers cannot operate without it. You could of course eat veggie burgers…. Or go total vegan….. And their is the option of foods made from ants and worms. Not my cup of tea. I suggest you fill up your freezer and let someone else worry about the shortages. This is not new. We have been urging you to stock up all year. In a food inflation your yielding more on your survival stash of foods then in your treasuries….
(Bloomberg) — Growing investor angst about China’s real estate crackdown rippled through markets on Monday, adding pressure on Xi Jinping’s government to prevent financial contagion from destabilizing the world’s second-largest economy. Hong Kong real estate giants including Henderson Land Development Co. suffered the biggest selloff in more than a year as traders speculated China will extend its property clampdown to the financial hub. Intensifying concerns about China Evergrande Group’s debt crisis dragged down everything from bank stocks to Ping An Insurance Group Co. and high-yield dollar bonds. One little-known Chinese property developer plunged 87% before shares were halted.
Hong Kong’s benchmark Hang Seng Index slumped 3.3%, its biggest loss since late July. The selling also spilled over into the Hong Kong dollar, offshore yuan and S&P 500 Index futures. Holiday closures in much of Asia may have exacerbated the volatility, traders said.
Faced with uncertainty over how far Xi is willing to go with his market-roiling campaigns to achieve “common prosperity” and rein in overindebted companies, many investors are choosing to sell first and ask questions later. Interest payment deadlines this week on several Evergrande bonds and bank loans add another layer of risk as market participants brace for what could be one of China’s largest-ever debt restructurings. “The price action across several asset classes in Asia today is horrendous due to rising fears over Evergrande and a few other issues, but it could be an overreaction due to all of the market closures,” said Brian Quartarolo, portfolio manager at Pilgrim Partners Asia. Xi faces a tricky balancing act as he tries to reduce property-sector leverage and make housing more affordable without doing too much short-term damage to the financial system and economy. Mounting concerns that he’ll miscalculate are spreading ever-further beyond China-focused property developers and their suppliers.
“It’s what the Chinese would describe as trying to get off a tiger,” said Justin Tang, head of Asian research at United First Partners.
Chinese policy makers may be able to avoid a financial crisis, but the Evergrande ordeal could still inflict lasting damage to credit conditions and the economy, Societe Generale SA analysts wrote in a note on Monday. “The repercussions from Evergrande’s prospective collapse will likely contribute to China’s ongoing economic deceleration, which in turn anchors global growth and inflation, and casts a pall over commodity prices,” wrote analysts led by Phoenix Kalen, head of emerging-market strategy in London. Hong Kong real estate companies took the brunt of the selling Monday, with the Hang Seng Property Index tumbling 6.7% for its biggest drop since May 2020. Henderson Land plunged 13% and Sun Hung Kai Properties Ltd. sank 10%, the most since 2012. Chinese officials told Hong Kong developers that Beijing is no longer willing to tolerate what it calls monopoly behavior, Reuters reported Friday. The officials didn’t lay out a roadmap or a deadline, according to Reuters, which cited unidentified developers. Hong Kong’s government has long struggled to bring home prices under control amid outsized demand, limited supply and low borrowing costs. The city’s average property value was a world-beating $1.25 million as of June 2020, according to CBRE Group Inc. “This is a paradigm shift,” said Hao Hong, chief strategist at Bocom International, referring to the Reuters report. “People need to keep a close look.” Ping An Insurance declined 5.8% to a more than four-year low on concerns about its property-sector exposure. The company issued a statement Friday saying that its insurance funds have “zero exposure” to Evergrande and other real estate companies “that the market has been paying attention to.” Real estate accounts for about 4.9% of Ping An Insurance’s investments, versus an average 3.2% for peers, according to Bloomberg Intelligence. In credit markets, the average price of high-yield dollar notes from Chinese borrowers slid some 2 cents Monday, set for the worst decline in about a year. That dragged down prices in the broader market for Asian junk bonds by 1 to 2 cents, traders said. Even debt with investment-grade ratings was stung. Yield premiums on notes from Country Garden Holdings Co., China’s largest developer by sales, widened to a record. The Hong Kong dollar fell to the lowest level this month, while the offshore yuan declined for a third day. FTSE China A50 Index futures slid 3.2% in Singapore. Mainland financial markets are closed for public holidays until Wednesday, when Hong Kong will be shut. S&P 500 Index futures dropped 1.2%. Evergrande is scheduled to pay interest on bank loans Monday, with a one-day grace period. While details on the amount due aren’t publicly available, Chinese authorities have already told major lenders not to expect repayment, people familiar with matter said last week. Evergrande and banks are discussing the possibility of extensions and rolling over some loans, the people said. Payments due Thursday include $83.5 million of interest on an 8.25%, five-year dollar bond, Bloomberg-compiled data show. Evergrande needs to pay a 232 million yuan ($36 million) coupon on an onshore bond the same day. The developer’s stock sank by as much as 19% on Monday to the lowest level since 2011. Its dollar bond due 2022 was indicated down 3.1 cents on the dollar at 26 cents, set for a record low. Nick Note: Warning to ALL people buying into the stock and real estate markets. Throw in people chasing higher yield… The End is neigh!
United States stock indexes traded significantly lower on Monday amid a global selloff, driven by inflation concerns, as well as the surge in new COVID-19 infections. Over the weekend, media reported that the Washington-held Quad summit should lead to a new semiconductor partnership among participants. The Dow Jones Industrial Average slid 1.37%, or 473 points at 4:24 am ET, while the Nasdaq lost 1.05%, or 160 points. The S&P 500 plunged 1.18% or 52 points at the same time. Nick Note: This is getting out of hand. Part of the fear in the market is the silence by the Chinese government on its latest wipe out of investors…especially the stupid US funds and investment bankers…. How did they hook them in. Its the classic free money trap. CHASING HIGHER YEILDS. Evergrande bonds were paying 8% in the classic what you see is what you do not get! And for the record the owners of this debt are US retirement savers who log on to their IRA fund and check the yield……. . China is closed for 2 days another freeging holiday. My read is the Chinese government will intervene and bond investors will take up to a 80% hair cut. Before I jump off the bridge i need to get a read on what is going on. I see a China take over of Evergrande….. As to the China real estate crises its worse in the US……… And the reaction in the US markets is overdone. Do not get me wrong a wipeout is coming… It will come as the FED raises rates and cut of the 150 billion a month in direct stimulus
Israel’s top COVID-19 experts say that they view the Food and Drug Administration advisory panel’s decision to recommend vaccine booster shots only for Americans over the age of 65 or those in specific risk groups as a vindication of their own country’s massive inoculation campaign. Israel was the first country in the world to begin a widespread booster shot campaign this summer, and Israeli data was used during the FDA panel’s deliberations. Yet while Israel is now offering the booster shot to anyone over the age of 12, the advisory committee decided to limit it to specific high-risk populations for now. Leading experts in Israel have said over the past two days that they view the American panel’s recommendation as an acknowledgment that conditions differ between the two countries. “The FDA in principle confirmed that the third dose is safe,” said Prof. Nadav Davidovitch, director of the School of Public Health at Ben-Gurion University of the Desert, Be’er Sheva, and head of the Israeli Association of Public Health Physicians. Davidovitch added that “we need to remember the FDA did approve it for high-risk people with chronic diseases and also those at high risk because of their profession, such as health care workers of all ages. They have their own priorities and Israel has other priorities, because we started earlier. We also started with older people and then moved down and I think this is a very reasonable decision.” Israel began to offer the third dose to older citizens back in August because of rising concerns, later confirmed by new research, that the effectiveness of the existing COVID-19 vaccines began to wane after approximately six months. An Israeli study published last week showed that booster shots increase protection from infection over tenfold in those over 60, compared to those who received only a second shot of the vaccine months ago. The study used data on 1.14 million Israelis aged 60 and up who had received two doses of the vaccine by the end of August. It divided cases into two groups: one consisting of people who received two doses of the vaccine, and another consisting of people who received a third dose. The researchers found that at least 12 days after the booster shot, the rate of infection in the non-booster group was 11.4 higher than the booster group, while their rate of severe illness was 19.5 times higher. The peer-reviewed study was authored by 11 researchers, including Israel’s director of public health services, Dr. Sharon Alroy-Preis, who also spoke in front of the FDA panel and presented relevant data from Israel. Following the FDA panel’s decision, Alroy-Preis explained how Israel’s considerations differ from those of the United States. “We are three months ahead of the U.S. in the entire vaccination campaign’’, she told the Ynet news website. ‘’They don’t yet see the waning immunity [of the previous doses], but here it’s very apparent.’’ In a statement on Saturday, the Health Ministry also said that the United States is “several months behind Israel” in terms of vaccinating its citizens, many of whom are still within the window of maximum protection offered by the second dose of the vaccine. “At the point in time where Israel is at the moment, it is right for Israel to vaccinate the entire population aged 12 and older with the booster dose,” the ministry asserted. Prof. Ran Balicer, who heads a panel that advises the Israeli government on COVID policies, appeared to agree, tweeting that Israel’s health authorities also debated over several weeks whether to approve the first stage of the booster campaign, which was originally limited to those over 60. “The American decision from tonight is much broader than the one made back then in Israel,’’ he wrote. “I believe they too will gradually expand the recommendation.” In an interview with Channel 12, Dr. Ofer Levy, an Israeli member of the FDA advisory panel, concurred that Israel’s situation was different from that of the United States, where he said more data was necessary, adding that Israelis eligible for a third shot should get one, regardless of what was happening in other countries. On Saturday, the Israeli Health Ministry’s COVID dashboard reported 697 patients in serious condition, 484 of whom were not vaccinated at all. In other words, despite the fact that only 17 percent of eligible Israelis have not been vaccinated at all for COVID-19, the unvaccinated are now more than two-thirds of the country’s severe cases. Meanwhile, there were 158 serious cases of people who received two shots of the vaccine, and only 55 who had received a booster shot. Over the past week, 119 people have died of the virus, and nearly 60 percent of them were unvaccinated. The disparity is even more apparent when calculating per capita: For every death of an Israeli over 60 who received the booster shot, there are roughly 15 deaths of unvaccinated Israelis in the same age group. As of Sunday, 3,040,426 Israelis have received a booster, while 5,576,238 have received two doses and 6,062,338 have only received one. The FDA is expected to make its final decision on the third round of shots soon. It is not bound by the panel’s recommendation but will take it into consideration.
Israel has been one of the focal points of the pandemic in 2021 owing to its rapid rollout of COVID-19 vaccines. By late February, authorities had administered at least one dose to 50% of the population, with much of Israel’s immunisation programme using Pfizer vaccines. Society then in effect reopened across the summer of 2021. However, since then Israel has reported significant outbreaks, with over 10,000 confirmed new cases being recorded each day in early September. A main part of the problem has been vaccine coverage. After its fast start, Israel’s rollout slowed. There have not been any clear interruptions to vaccine supply, so factors such as hesitancy or access to healthcare may have been an issue. For example, there’s evidence of uptake being lower among Arab and ultra-Orthodox Jewish groups. The share of the population having received one dose increased from 50% in February to only 68% in September. Children aged 12-15 have been included in the rollout since June 2021, yet despite this, currently only 62% of the population have had two doses.This has left Israel behind many other countries in terms of coverage, including the UK. Having around 30% of the Israeli population completely unvaccinated means that there’s approximately 2.7 million people who are potentially susceptible to infection and illness. There are also concerns that the immunity offered by the Pfizer vaccines may be waning over time, although much of the research on this is still at an early stage (meaning it is still awaiting review by other scientists). Israel’s hospital data is, though, showing that vaccinated people are susceptible to infection. Recent reports suggest that nearly 60% of hospitalisations are in the fully vaccinated. However, as experts have suggested, these figures don’t necessarily mean that vaccines have lost their effectiveness. The same sort of trend has been seen in the UK, and may simply reflect the fact that the elderly are more likely to be vaccinated while also being more susceptible to disease – factors which combine to inflate COVID-19 cases and deaths among the vaccinated.
A further factor is the more transmissible delta variant, which has now taken hold in Israel. This form of the virus is driving the current series of outbreaks, and its greater ability to spread may partially explain the rise in cases too.
The other big part of the problem has been Israel ending its restrictions. Dr Asher Salmon, director of the Department for International Relations at Israel’s ministry of health, suggested in July that Israel “may have lifted restrictions too early”. It’s the latest in a long line of examples showing how community transmission can be easily sustained when national policy encourages the mixing of susceptible people with no or few restrictions in place. The tragic consequences of relaxing restrictions in India shows how devastating it can be when decision-making goes awry. The COVID-19 Stringency Index created by Our World in Data is a composite measure of the strictness of the COVID-19 containment policies in each country around the world. As of August 28 2021, Israel’s restrictions score was 45.4, far less strict than New Zealand, where outbreaks continue to be limited in scope (96.3), but comparable with the UK (44.0), which is reporting around 30,000 new cases per day. Countries watched the initial vaccine rollout in Israel, gauging the vaccines’ impact and using this information to inform their own immunisation campaigns. Amid concerns about waning immunity, there are once again reasons to observe what happens next in Israel, as it is now implementing a booster programme, giving third doses of vaccines.
In terms of the effectiveness of boosters, early reports are encouraging. In those receiving a booster, the risk of a confirmed coronavirus infection appears to decrease 11-fold relative to individuals who have received two doses. However, the relevant study is still in preprint, so its findings have yet to be formally reviewed.
The use of boosters is controversial. There have been continuous calls for higher-income countries to share their vaccine stockpiles with lower-income ones. This has not yet happened to any great extent. As of early September, only 5.4% of the African continent has received at least one dose of any COVID-19 vaccine. The World Health Organization has called for a moratorium on booster shots until at least the end of September, but it seems unlikely any country will be altering their policies accordingly – including Israel. Israel’s vaccine rollout, overall, has arguably been implemented very successfully. But the country is also an example of what can happen when restrictions are relaxed too quickly. What it shows is that all countries – regardless of their current vaccine status – need to maintain longer-term plans for how to minimise the impact of COVID-19, during this current pandemic and beyond when controlling smaller outbreaks.
Nick Note: Lets keep our perspective here. This is not about politics. Its not even about who is right and who is wrong. Its about staying healthy and alive. I am seeing a lot of confusion about the record breaking infections in Israel. The data suggest that is caused by 3 things.
1. the highly infections and more deadly Delta mutation.
2, it is infecting non vaccinated people in droves.
3. To a much lesser extent we are seeing a increase in what is called breakthrough infections among the fully vaccinated as their vaccine wears off in 6 month.
For the record serious infections among the 3rd vaccinated are nill. We are seeing hospitalizations among unvaccinated at a rate 500 cases per hundred thousand. Among (2 shot) vaccinated 20 cases per 100,000. And among the fully vaccinated with the 3rd shot 1 case, one serious ill person out of 100,000. So why are cases at record highs in Israel. Well the truth is its being driven by two things… The fools unvaccinated and the lifting of ALL restrictions for the high holidays. That represent from the Jewish New Year to Succot weeks of get togethers in big groups. And the festive season is not over yet. So fasten your seat belt. The good news is we will get incredible accurate data. Early indicators will show that triple vaccinated people are not getting infected.
(Bloomberg) — Bond bears, long frustrated by stubbornly low Treasury yields, are girding for a make-or-break week as the Federal Reserve is expected to start laying the groundwork for reducing stimulus. The bond market enters this potentially pivotal stretch at a crossroads: 10-year yields are testing the top of their range since early July as traders anticipate that the Federal Open Market Committee will hint in its Sept. 22 decision at a plan to curb its bond buying. For the bearish contingent, which is the majority on Wall Street, this meeting represents one of the last prospective triggers this year for a decisive breakout in yields. Primary dealers surveyed by Bloomberg News predict on average that 10-year rates will be more than 30 basis points higher by year-end. Fed tapering signals are hardly the only focus. Strategists also see likely ammunition for bears in the central bank’s new forecasts for its benchmark rate. An unexpected hawkish shift in these projections in June jolted financial markets and flattened the yield curve by the most since the early days of the pandemic. “My view has been that the September FOMC will be a potential catalyst to get things moving toward higher yields by year-end,” said Blake Gwinn, a strategist at RBC Capital Markets, who expects 10-year yields to rise to 1.75% next quarter. “If that fails to materialize, I am not sure if other catalysts will get us there, and we may be stuck in range-bound trading in Q4.” The average forecast in a Bloomberg survey of primary dealers is for benchmark 10-year yields to climb to 1.69% by year-end, from a bit under 1.4% now. Deutsche Bank AG was the most bearish, forecasting 2.25%. HSBC Holdings Plc’s Steven Major, known for his persistent bullish views, had the lowest forecast, at 1%. The Fed is likely to hint Wednesday that it’s ready to taper soon with a formal announcement coming in November, according to a separate Bloomberg survey of economists. The central bank is also expected to hold rates near zero through 2022 before delivering two quarter-point increases in 2023 and three more the year after. The risk is that a hawkish shift in Fed projections known as the “dot plot” will prompt traders to recalibrate expectations for the central bank’s policy path, as happened in June. It will take just three officials to raise their dots for 2022 for a full hike to be the new median for next year, assuming everyone else keeps their forecasts where they were. Such a scenario would leave 5- and 10-year Treasuries particularly vulnerable to a selloff, according to Subadra Rajappa, head of U.S. rates strategy at Societe Generale. Expectations of such a shift have already contributed to shrinking the 5- to 30-year yield spread to the smallest since August 2020, when the Fed unveiled its new inflation framework. In options, bets emerged Friday on even higher 5-year yields. “The dots in next week’s meeting is going to be very important, not just for 2024, but also for 2022,” said Rajappa, who sees 10-year yields at 1.7% at year-end. “We believe this is an underpriced risk and bodes well for our call for higher yields.”
What to Watch
The economic calendarSept. 20: NAHB housing indexSept. 21: Building permits; current account balance; housing startsSept. 22: MBA mortgage applications; existing home sales; FOMC decisionSept. 23: Chicago Fed national activity index; jobless claims; Langer consumer comfort; Markit PMIs; leading index; Kansas City Fed manufacturing activity; household change in net worthSept. 24: New home salesThe Fed calendarSept. 22: FOMC decision and press conference by Fed Chair Jerome PowellSept. 24: Cleveland Fed’s Loretta Mester; Powell, Governor Michelle Bowman and Vice Chair Richard Clarida host Fed Listens event; Kansas City Fed’s Esther GeorgeThe auction calendar:Sept. 20: 13-, 26-week billsSept. 21: 20-year bondsSept. 22: 2-year floating-rate notesSept. 23: 4-, 8-week bills; 10-year TIPS.
Nick Note: You need to liquidate ALL your bonds. Some of you are holding US TREASURY BONDS either at treasury direct or at your broker. Interest rates have bottomed for now. We need to get ahead of this. As discussed in previous postings inflation is embedded and inflationary expectations as is the rise in inflation are at record rates. I am not referring to out beloved Zeroes Principal portion strips. i had you take profits on when they dropped below 2%. Rates on all issues will be going higher…. The fed is 400 to 500 bases points behind the power curve. So lets take profits on all your Treasury bonds and and bills of maturity over a year or more. Please note after they stamp out inflation (they will have to collapse the economy to do it. Like they have done every other time.) We will buy back out strips and bonds on the coming upward spike in rates… And then we will ride them down to double digit negative as the economy wipes out…. again.
BAGHDAD — OPEC and its allies will try to keep oil prices at $70 per barrel in the first quarter of 2022, Iraq’s oil minister said, adding the group is expected to stick to its current production accord when it meet in October “if prices remain stable.” Iraq total oil exports, including those of the Kurdistan region in the north of the country, should stand at an average of 3.4 million barrels per day in September, the minister, Ihsan Abdul Jabbar, told a news conference in Baghdad on Sunday.
OPEC and its allies agreed to stick to their existing plan for gradual monthly oil-production increases after a brief video conference. Ministers ratified the 400,000 barrel-a-day supply hike scheduled for October after less than an hour of talks, one of the quickest meetings in recent memory and a stark contrast to the drawn-out negotiations seen in July.
“OPEC have proven once again that they can meet and do things seamlessly,” Christyan Malek, head of oil and gas and JPMorgan Chase & Co., said on Bloomberg TV. “It’s likely that harmony is going to be utilized” to respond flexibly to any further shifts in the market over the coming year, he said.
While conditions may appear favorable for cartel right now, there are uncertainties on the horizon. Even as demand recovers, it has been buffeted by the emergence of new coronavirus variants. The question of whether Iran and the U.S. will do a deal to lift sanctions on the Islamic Republic’s oil exports — currently looking less likely — also hangs over the market. The Organization of Petroleum Exporting Countries and allies including Russia are in the process of rolling back the unprecedented output cuts implemented at the depths of the Covid-19 crisis last year. About 45% of the idle supply has already been revived, and in July the group laid out a plan for gradually returning the remainder through to September 2022. With crude prices mostly recovered from their mid-August slump and the supply outlook relatively tight for the rest of the year, the 23-nation coalition had little reason to change the established schedule of gradual monthly supply hikes, despite a request from the White House to revive output faster. There had been some doubts about the plan when oil markets wobbled over the summer as the resurgent virus threatened demand. But fuel use proved resilient, with total oil products supplied in the U.S. rising to a record in late August. “While the effects of the Covid-19 pandemic continue to cast some uncertainty, market fundamentals have strengthened and OECD stocks continue to fall as the recovery accelerates,” OPEC+ said in a statement. The group will meet again on Oct. 4. Data presented to ministers reveal a fresh challenge for Saudi Arabia and its partners in 2022. Markets were projected to tip back into surplus next year, with an average oversupply of 1.6 million barrels a day. However, the projections assume the group will restore all of the almost 6 million barrels a day of output that remains offline — an unlikely feat as many countries may struggle to reach their full targets. The amount of crude production that OPEC+ theoretically holds offline is based on questionable figures. Russia has an inflated baseline that’s significantly higher than pre-pandemic output. Some other members have outdated capacity numbers, with countries including Angola and Nigeria already struggling to make the supply increases permitted under the deal. Nick Note: Oil lives and dies on the state of the global economy visa vie the spreading Covid19 mutant strains. And how fast the FED caves in and raises rates and pulls liquidity from the system…..